New Jersey adopts a QSBS capital gains exclusion (A4455)
New Jersey now excludes gain on qualified small business stock similar to federal Section 1202, removing up to 10.75% state tax on qualifying start-up exits.
The higher SALT deduction cap opens a larger federal write-off for some homeowners in high-tax areas, but a phase-down above $500,000 of MAGI and regional gaps sharply limit who benefits.
Retroactive to January 2026, New Jersey's FY27 budget cuts off the personal offset tied to the state's pass-through entity tax for owners with more than $1 million in income.
By declining to hear Murrin v. Commissioner, the justices let stand a Third Circuit ruling that the IRS can assess tax at any time on a fraudulent return, even when only the preparer intended to cheat.
California's combined top marginal rate reaches 14.4% and NYC residents face up to 14.776%, even as Georgia, Indiana, Kentucky and six other states cut income tax rates on January 1.
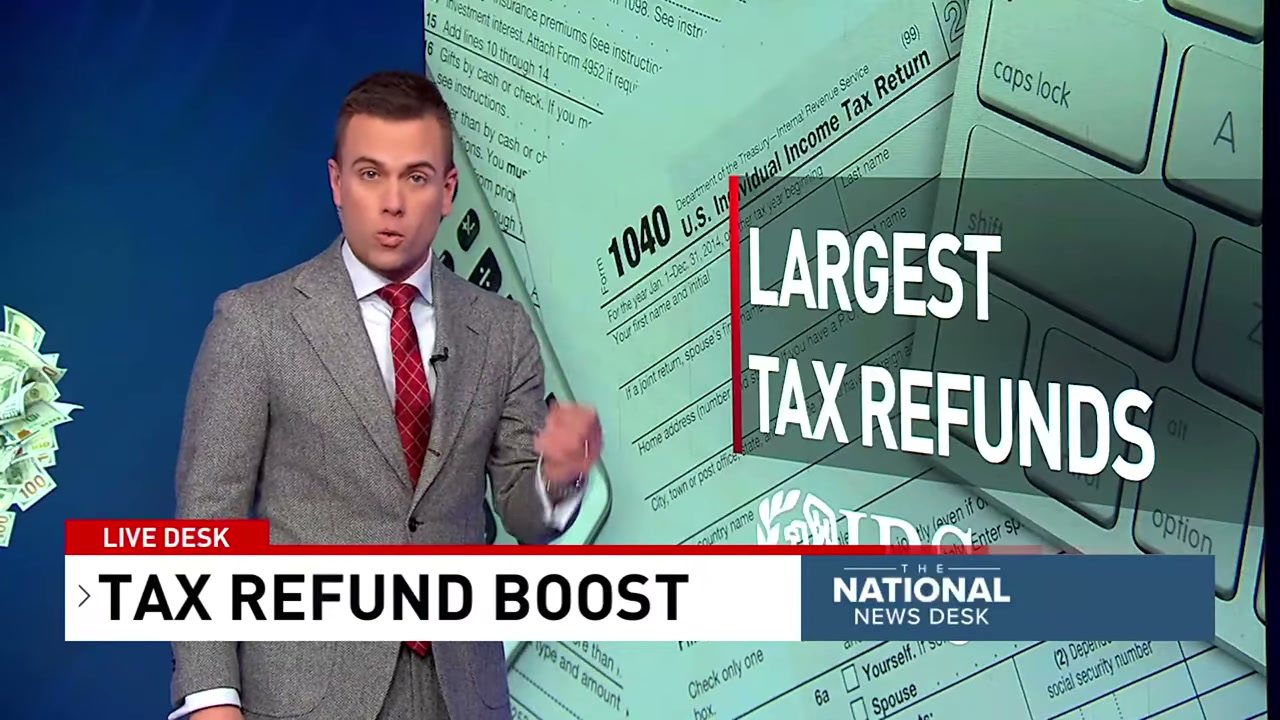
The 2025 tax law cut individual taxes by about $129 billion, but paycheck withholding was never updated, so much of that cut, including the $40,000 SALT cap, arrives as a refund this spring.
The new deduction limit loses 30 cents for every dollar of income above $500,000, and a faster AMT exemption phaseout from 2026 adds pressure on high earners in high-tax states.