Coverage
Retirement
401(k)s, IRAs, Roth conversions and required distributions.
34 stories
A Sept. 17 report highlighted how Realty Income’s monthly REIT dividend can be shielded from federal tax inside a qualified Roth IRA, while the same payments in a taxable account are generally taxed at ordinary income rates.
A SECURE 2.0 rule now requires many workers age 50 and older with prior-year wages above $150,000 to put 401(k) catch-up contributions into a Roth account, ending the upfront federal tax break on that slice.
The IRS said some SECURE and SECURE 2.0 retirement plan amendments may be due after Dec. 31, 2026, depending on when the agency places a provision on its Required Amendments List.
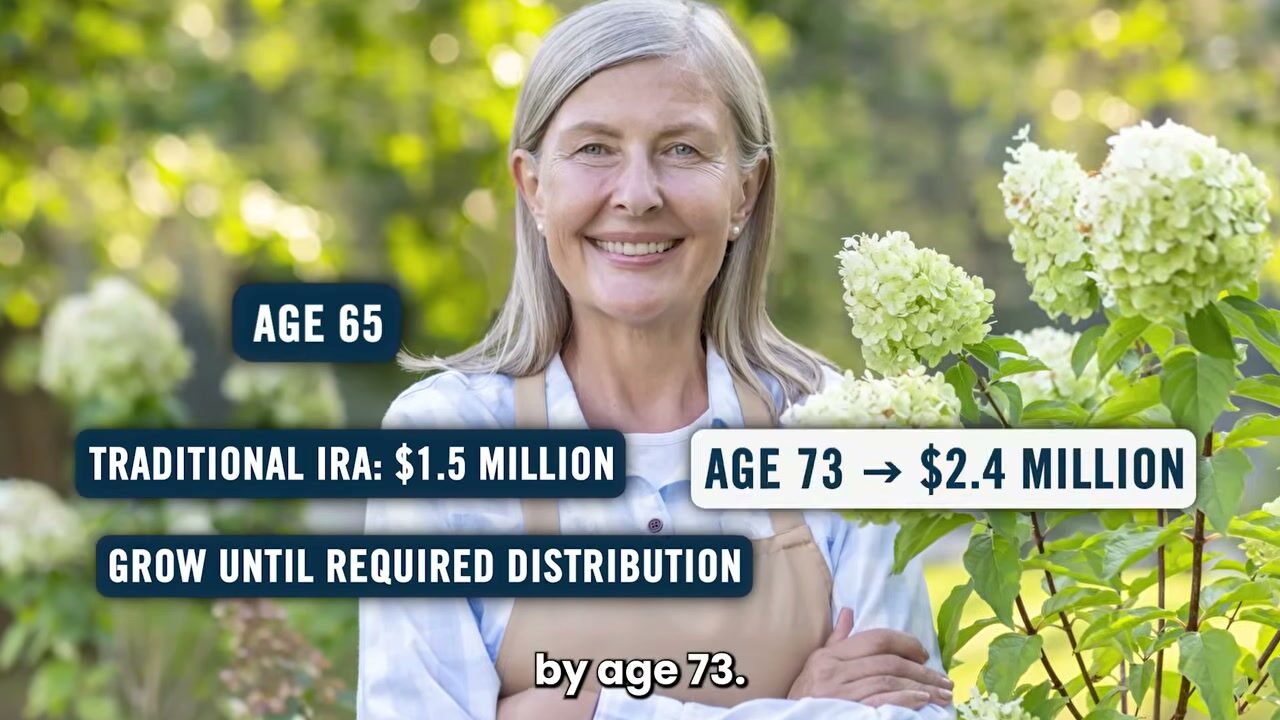
A new example making the rounds among retirement planners shows how affluent couples in their early 60s may use low-income years before age 73 to shift a large 401(k) into Roth accounts while managing tax brackets and Medicare surcharges.
The IRS says new sample forms and standardized rollover procedures are meant to streamline plan-to-plan and plan-to-IRA transfers, while Treasury weighs tougher limits on paper checks and other hurdles.
Families funding Trump Accounts in 2026 have until Dec. 31, but employer contributions and pretax paycheck deferrals can also count toward the $5,000 annual cap and raise overfunding risk.
A first required minimum distribution can raise taxable income twice: once through the IRA withdrawal itself and again by pulling more Social Security benefits over long-frozen taxability thresholds.
A growing retirement playbook for higher-asset couples is to use the low-income years after work ends for Roth conversions, then delay Social Security to 70 to raise lifetime and survivor benefits.
Fidelity's record count of 769,000 401(k) millionaires puts a spotlight on pretax balances that required distributions will force out at 73 or 75, often alongside taxed Social Security and higher Medicare premiums.
Fidelity's second-quarter data shows seven-figure 401(k) accounts jumped from 645,000 to 769,000 as stocks rallied, leaving more savers with large pretax balances that will eventually be taxed.
Inflation and health care top retirees' worries. For affluent households, the written plan that eases stress is largely a tax plan covering withdrawals, conversions and Medicare premiums.
Notice 2026-49 lays out optional sample forms and a five-step process for direct rollovers under SECURE 2.0, and signals future rules that could end mailing rollover checks to participants.
Contributions opened July 4 and the first investments followed on July 6. Families can put in after-tax money, but growth is taxed as ordinary income once the child reaches adulthood.
The 25th How America Saves study shows record 401(k) participation and savings rates, but finds most high earners still leave mega-backdoor Roth and after-tax contribution room unused.
The 2026 Trustees Report pulls the retirement trust fund's depletion forward a year and widens the 75-year gap by 16%, partly because the 2025 tax law cut revenue from taxing benefits.
Rev. Proc. 2026-24 lifts health savings account contribution caps by $100 and $250 for 2027 and confirms that small direct primary care fees no longer block eligibility.
Northwestern Mutual's 2026 Planning & Progress Study found the self-reported retirement number keeps climbing, and the gap is even wider for savers who hold most of their nest egg in pretax accounts.
The IRS says a quarter of enrollees qualify for the $1,000 federal seed deposit, giving affluent families a new window to layer Trump Accounts with 529 plans and gifting strategies.
Two sets of proposed IRS regulations explain who can open a child's Trump Account, how parents claim the $1,000 Treasury contribution and what families should know before deposits begin July 4, 2026.
Fidelity's year-end account data shows average retirement balances rising by double digits, a milestone that also foreshadows larger required withdrawals — and tax bills — down the road.
Comment letters filed by February 20 ask Treasury to open Trump Accounts to competing IRA providers, fix a rollover glitch and confirm fees, shaping where a child's account will actually live.
The model 402(f) explanations plans give departing employees now cover new penalty exceptions, a $7,000 cashout limit, RMD ages 73 and 75, and the end of RMDs for plan Roth accounts.
Fidelity's year-end guidance walks through the tax moves that still matter for 2026, from Roth conversions and the new $6,000 senior deduction to RMD deadlines and charitable-giving limits.
 September 17, 2026 at 1:37 PM PDT