REG-116506-25 would require opportunity funds to report investor dispositions, have zone businesses attest to compliance and follow new decertification steps, with comments due October 16.
An art broker who spent a partner's unrestricted wire on a separate painting owed tax on the money in the year it arrived, the court held, because nothing at the time made it a loan or a deposit.
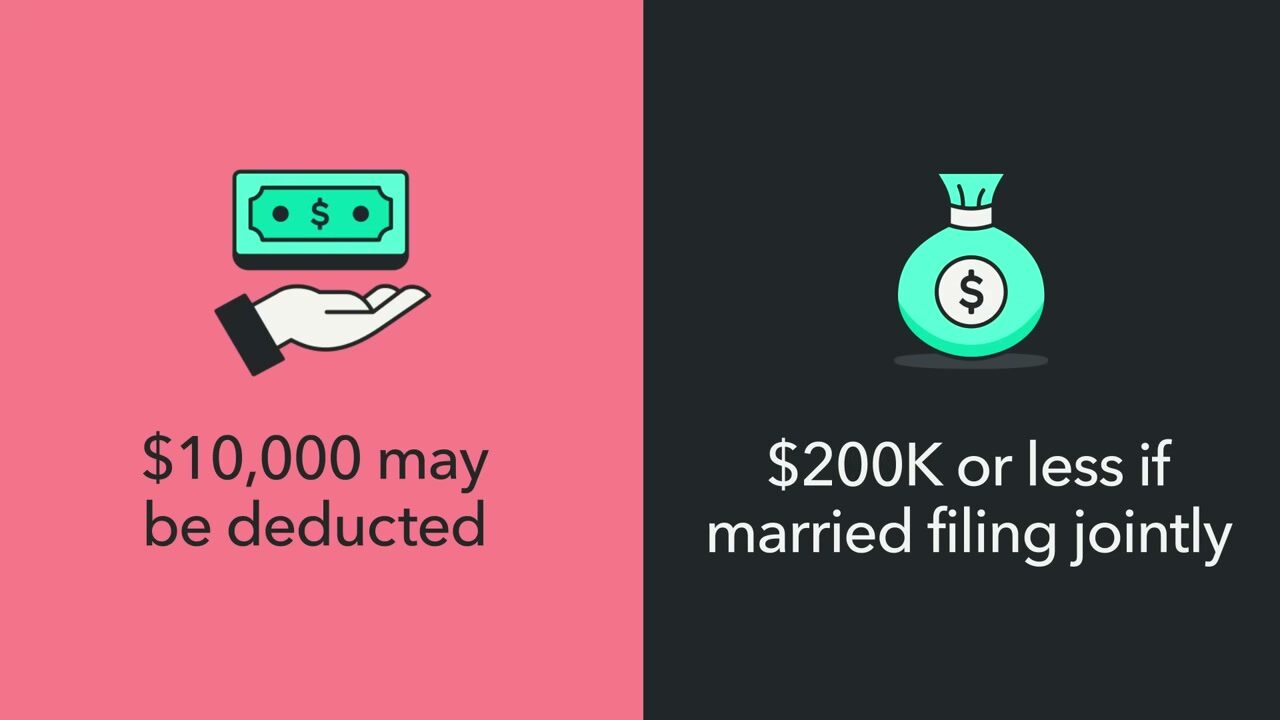
T.D. 10054 finalizes the deduction for interest on loans for new U.S.-assembled vehicles, but income phaseouts that begin at $100,000 and $200,000 limit its value for high earners.
The Fourth Circuit ruled a businessman recklessly failed to report Hong Kong and Swiss accounts, and that a penalty near 30% of the statutory maximum was not grossly disproportional.
Rev. Proc. 2026-32 updates the automatic change procedures for Section 174A research expensing and residential construction contracts, with a shorter Form 3115 and relief for returns already filed.
Companion rulings in Bruyea and Christensen say neither the U.S.-Canada nor U.S.-France tax treaty lets a foreign tax credit offset the net investment income tax, exposing expatriates to double taxation on investment income.
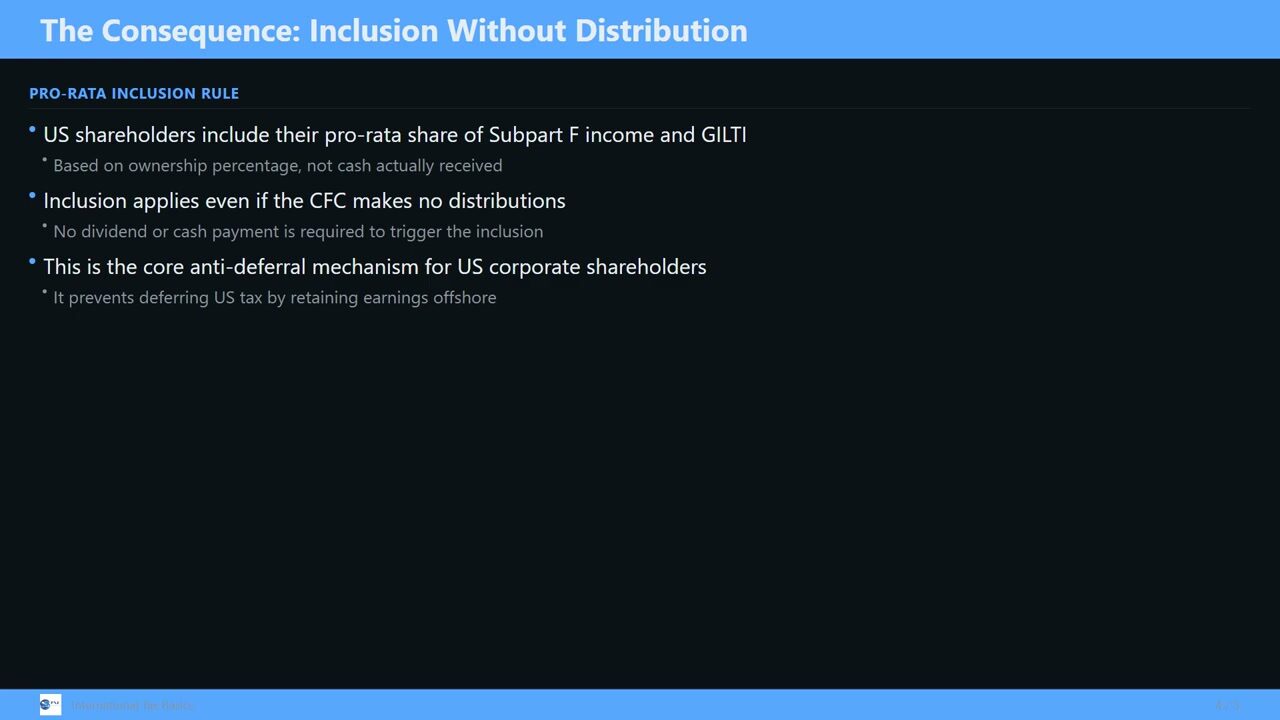
Proposed regulations would tax a founder's or investor's share of a foreign subsidiary's income based on how many days they held the shares, closing a planning window that let a mid-year seller escape the tax entirely.
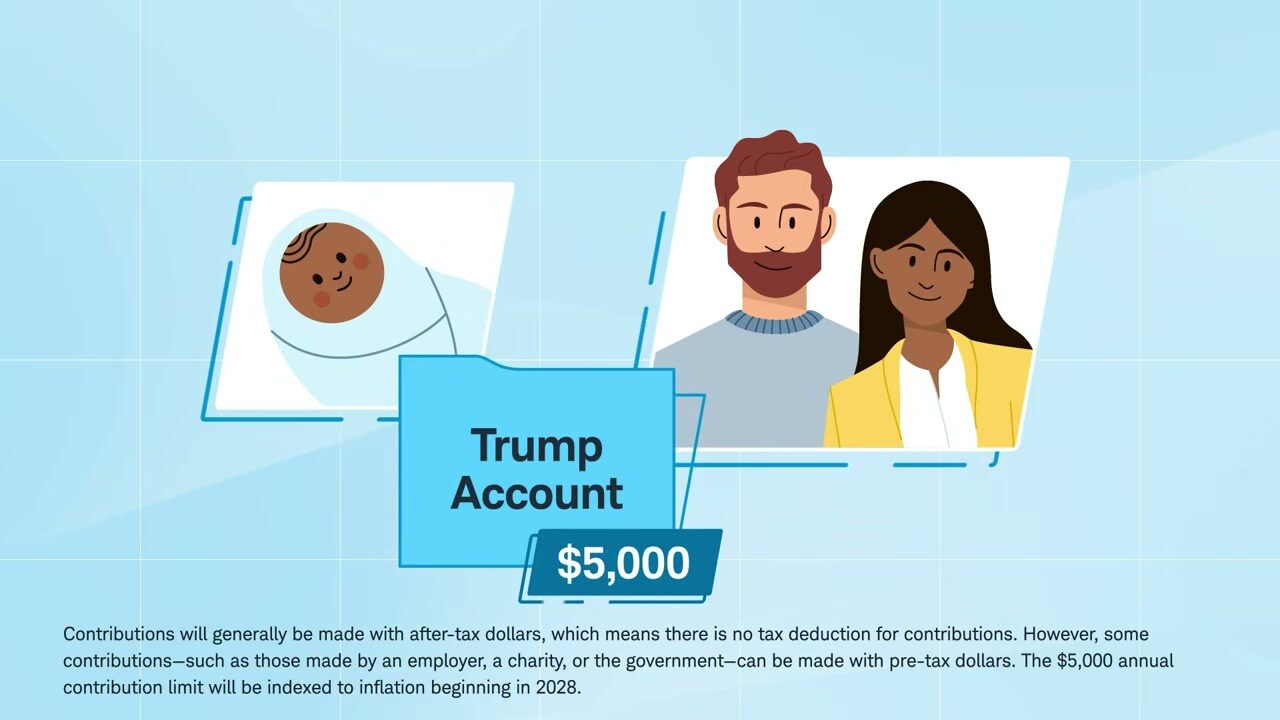
Treasury’s August 20 proposal bars sector, ESG and leveraged funds from Trump Accounts until the year a child turns 18, and caps fund costs at a tenth of a percent.
IRS
We have no commercial relationship with this firm, and a listing here is not a recommendation. General information, not tax, legal or investment advice.