The Internal Revenue Service on Oct. 9 published the inflation-adjusted figures that will govern tax year 2026, the first annual set to reflect changes from the One, Big, Beautiful Bill signed in July. For high-income households, the release pins down where the 37% bracket begins, how much wealth can pass free of estate tax and how much can be given each year without touching the lifetime exemption.
What changed
According to the IRS announcement (IR-2025-103) and the underlying Revenue Procedure 2025-32, the seven rates are unchanged, but every bracket threshold moves up. The standard deduction for married couples filing jointly rises to $32,200, an increase of $2,200, according to KPMG's summary. Single filers get $16,100 and heads of household $24,150. The personal exemption stays at zero.
| Rate | Married filing jointly, taxable income over | Single, taxable income over |
|---|---|---|
| 22% | $100,800 | $50,400 |
| 24% | $211,400 | $105,700 |
| 32% | $403,550 | $201,775 |
| 35% | $512,450 | $256,225 |
| 37% | $768,700 | $640,600 |
On the transfer-tax side, the basic exclusion amount for estates of people who die in 2026 is $15 million, up from $13.99 million for 2025. The annual gift exclusion holds at $19,000 per recipient, the same as this year.
Who is affected
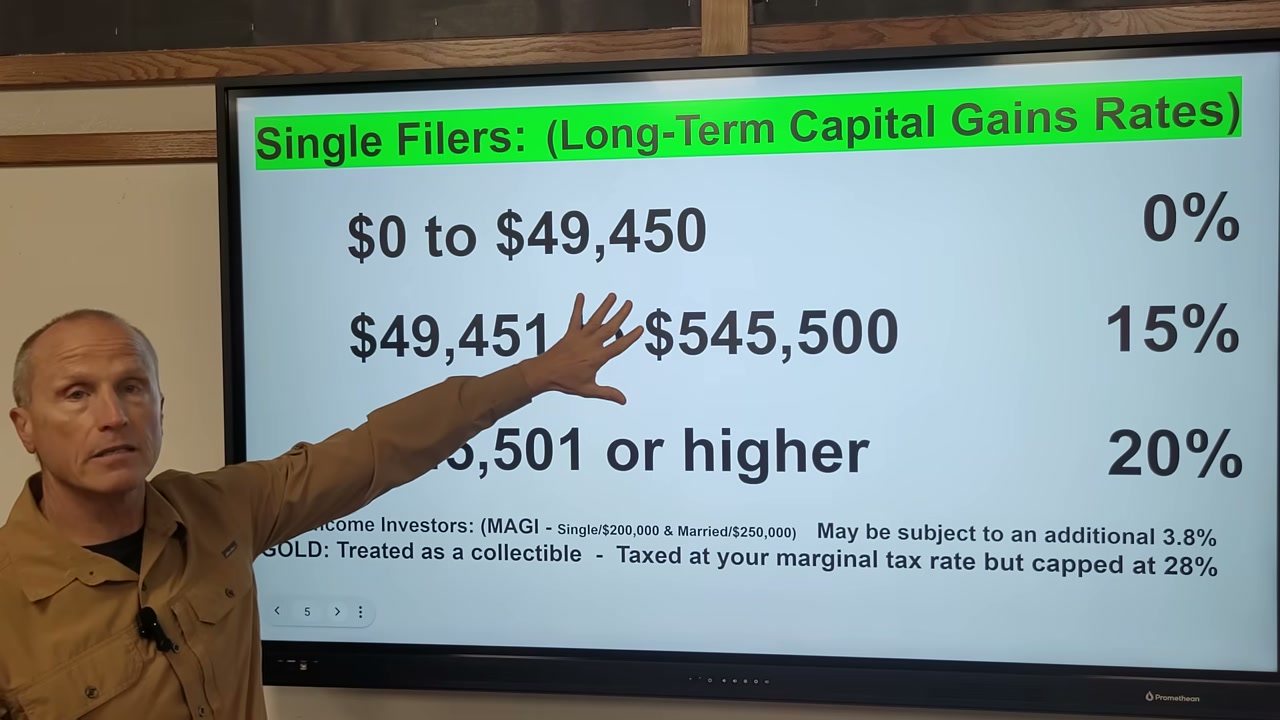
The capital gains breakpoints matter as much as the ordinary brackets for investors. For 2026, the 0% rate on long-term gains and qualified dividends applies to joint filers with taxable income up to $98,900, and the 15% rate runs up to $613,700; above that, the 20% rate applies. For single filers the figures are $49,450 and $545,500, and for heads of household $66,200 and $579,600.
Trusts and estates face a far steeper schedule. Their 15% capital gains band ends at just $16,250 of taxable income, which means a nongrantor trust holding a concentrated position can reach the top capital gains rate on a small fraction of what a married couple would.
The alternative minimum tax exemption is $140,200 for joint filers and $90,100 for single filers, with phase-outs beginning at $1 million and $500,000 of alternative minimum taxable income, respectively. Other figures in the release include a $132,900 foreign earned income exclusion and a $3,400 limit on health flexible spending account contributions. Families with children earning investment income should note the kiddie tax figure of $1,350; a parent can elect to report a child's income only when the child's gross income is more than $1,350 but less than $13,500.
The after-tax math
Example: a married couple expects $900,000 of taxable income in 2026. Only the slice above $768,700, or $131,300, is taxed at 37%. The next $256,250, between $512,450 and $768,700, is taxed at 35%. If the couple could move $50,000 of income out of 2026 through a deferral arrangement or additional deductions, the federal income tax saving on that slice would be $18,500 at the 37% rate.
Gifting example: the $19,000 exclusion applies per donor and per recipient. A couple with three children and three grandchildren could give $19,000 from each spouse to each of the six recipients, moving $228,000 out of their combined estate in 2026 without using any of the $15 million per-person exclusion.
Trust example: a nongrantor trust with $200,000 of long-term gains in 2026 would have most of that gain above the $16,250 breakpoint and taxed at 20%. The same gain reported by beneficiaries who are married and have $300,000 of other taxable income would sit inside the 15% band, which ends at $613,700.
Moves to discuss with your advisor
- Whether year-end 2025 income, bonuses or deductions are better recognized this year or shifted into 2026 given the new bracket edges.
- How the $15 million exclusion and $19,000 annual exclusion fit an existing gifting schedule, including gifts to trusts.
- Whether trust distributions could shift capital gains to beneficiaries in lower brackets, a question worth discussing with a CPA or estate attorney.
- For households with large incentive stock option exercises, where the $1 million AMT phase-out threshold falls relative to expected income.
What to watch
The release covers the inflation-indexed items only. Other provisions of the July law, including changes to itemized deductions, are handled in separate guidance and forms. Payroll withholding tables and draft 2026 forms typically follow in the coming months, and they will translate these thresholds into paychecks. Households that pay estimated taxes may want to recheck 2026 projections once those tables are out.
Sources
After TAX is an independent publication. Articles are general information, not tax, legal or investment advice. Consult a licensed professional about your situation.



