A Treasury and IRS proposal would let private schools lose Section 501(c)(3) status for race-based admissions, scholarships, or programs, raising donor, endowment, and financing stakes across the sector.
A California appeals court said San Francisco’s voter-approved Empty Homes Tax conflicts with state law, leaving a levy of $2,500 to $20,000 per vacant unit unenforceable for now.
A September 12 reminder from a Naperville enrolled agent firm underscores a federal tax rule many divorced filers miss: a state divorce order does not bind the IRS on a joint return, though relief may still be available under Section 6015.
AppraiseItNow said it now offers expedited appraisal reports for Forms 8283, 709, and 706 nationwide, a service aimed at taxpayers, executors, attorneys, and advisors facing tight filing deadlines.
REG-116506-25 would require opportunity funds to report investor dispositions, have zone businesses attest to compliance and follow new decertification steps, with comments due October 16.
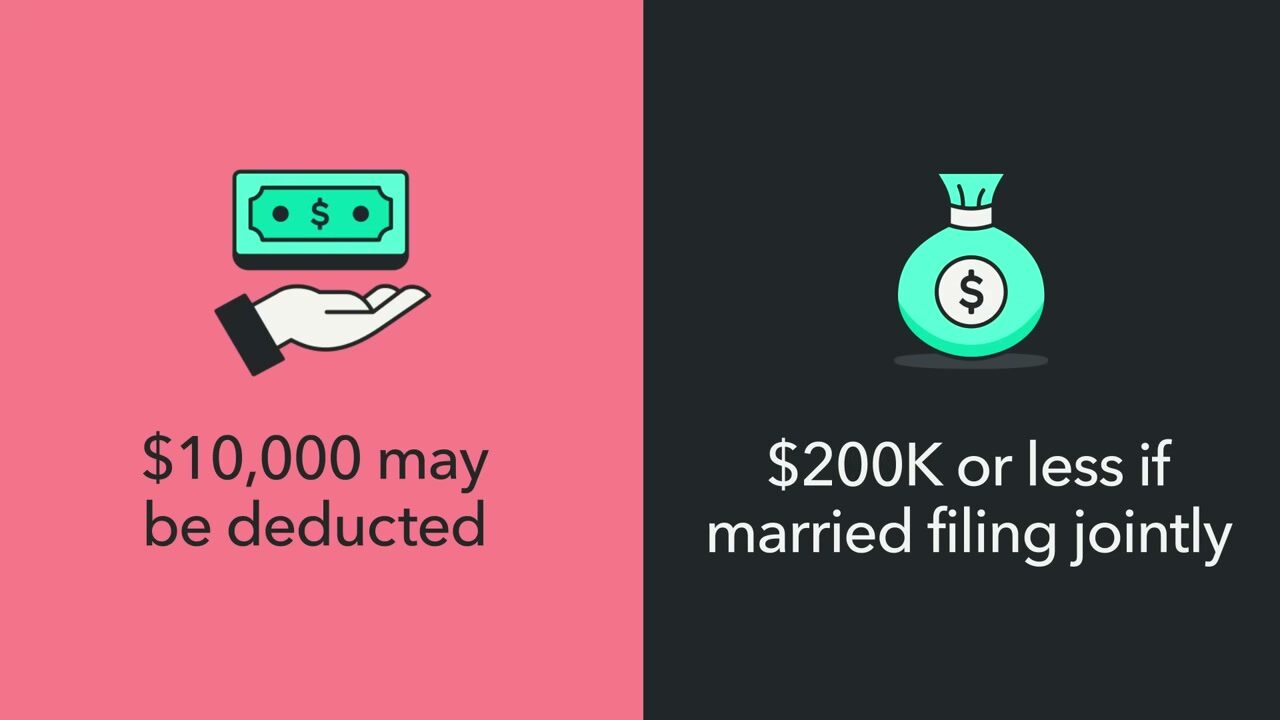
T.D. 10054 finalizes the deduction for interest on loans for new U.S.-assembled vehicles, but income phaseouts that begin at $100,000 and $200,000 limit its value for high earners.
Rev. Proc. 2026-32 updates the automatic change procedures for Section 174A research expensing and residential construction contracts, with a shorter Form 3115 and relief for returns already filed.
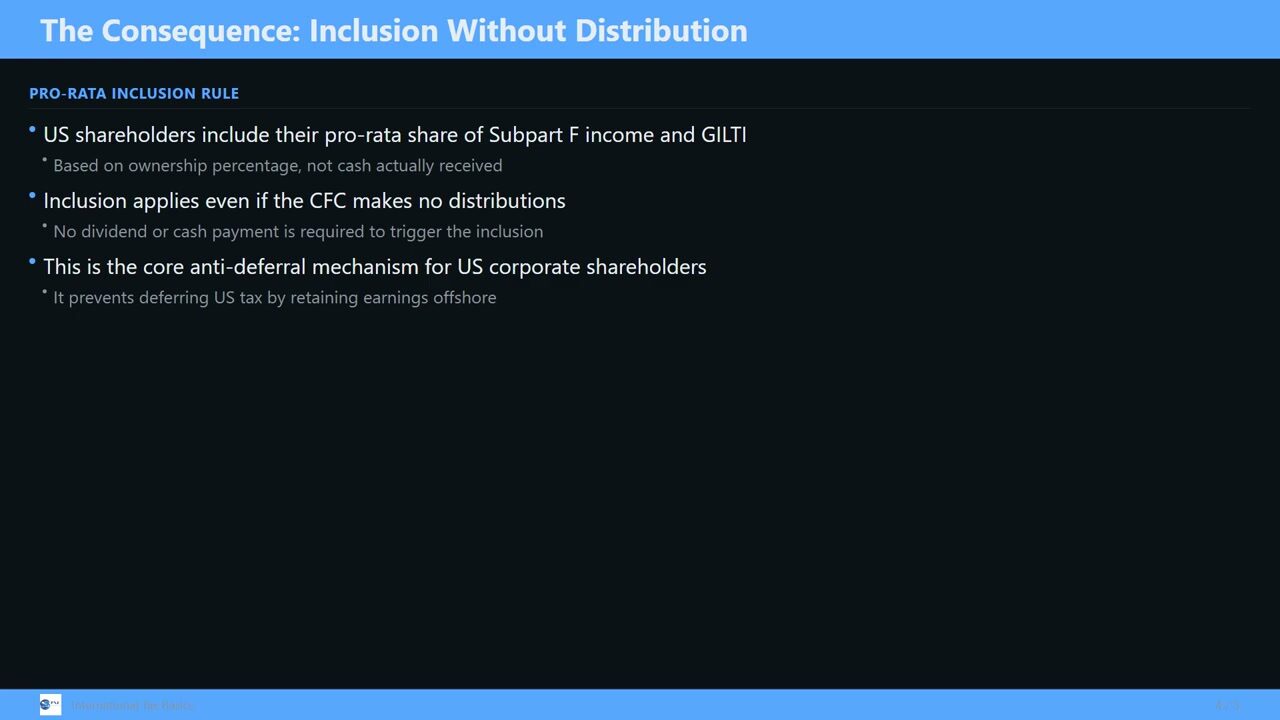
Proposed regulations would tax a founder's or investor's share of a foreign subsidiary's income based on how many days they held the shares, closing a planning window that let a mid-year seller escape the tax entirely.
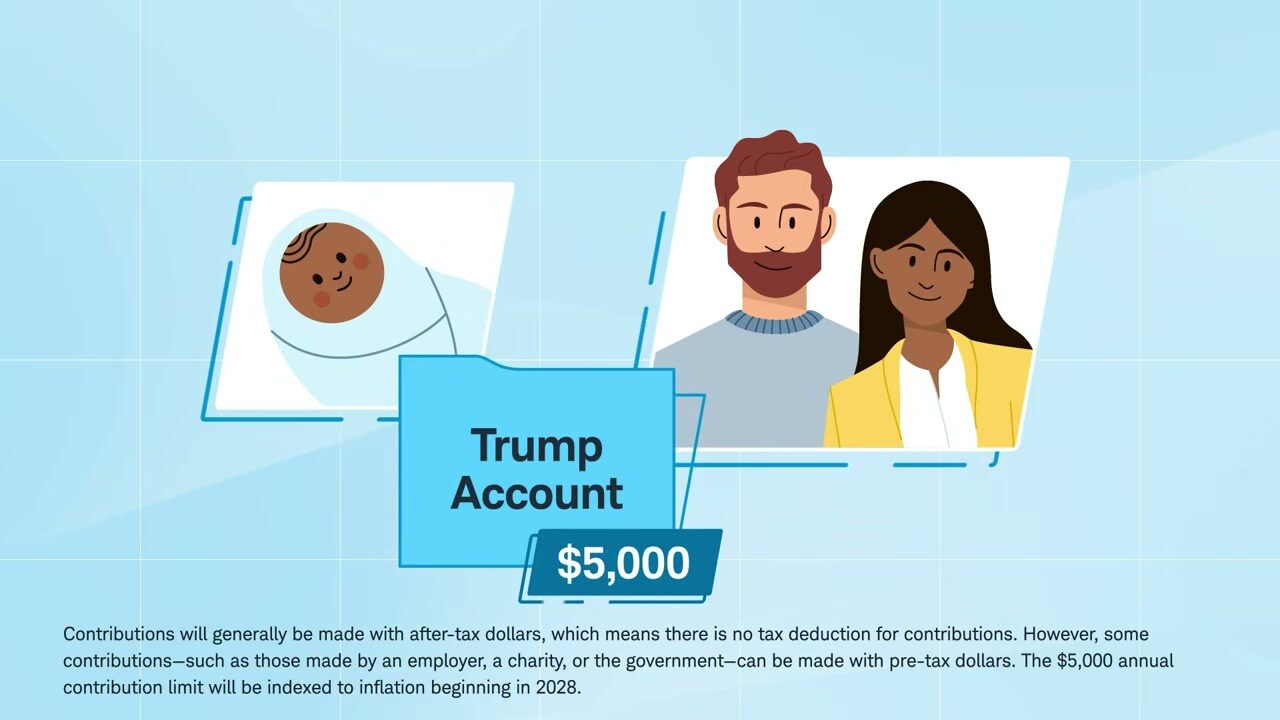
Treasury’s August 20 proposal bars sector, ESG and leveraged funds from Trump Accounts until the year a child turns 18, and caps fund costs at a tenth of a percent.
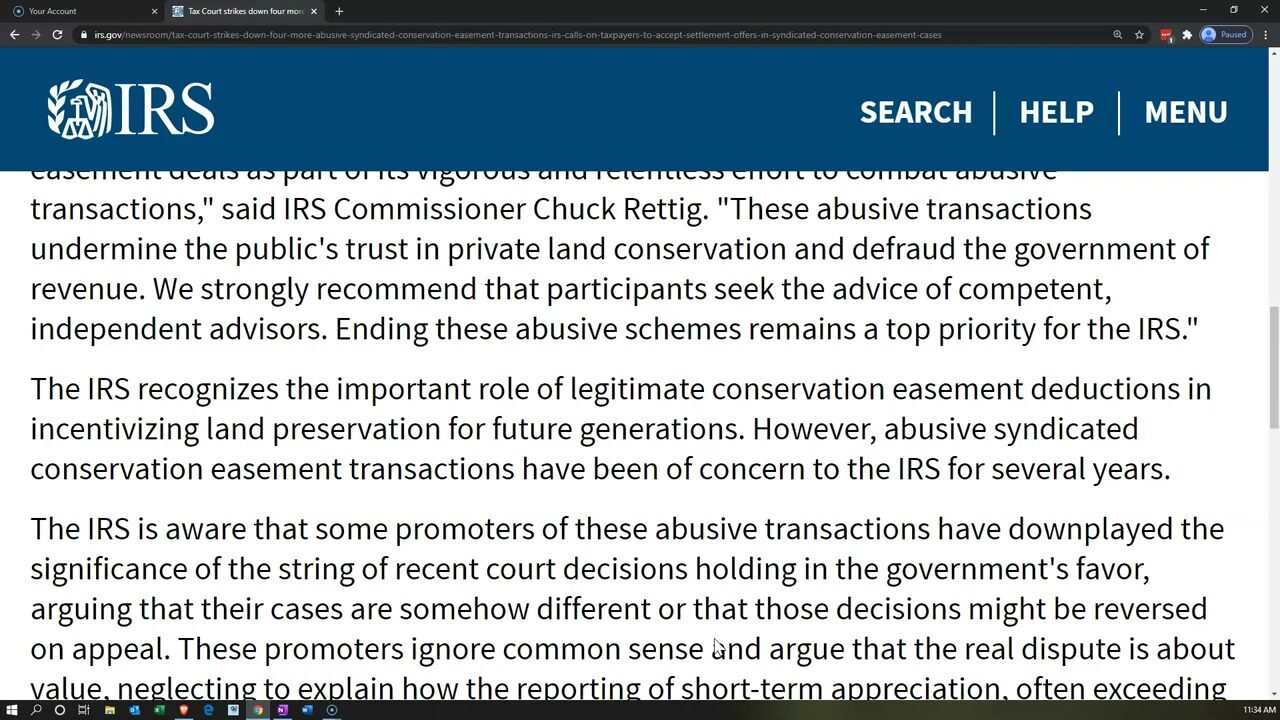
The Eleventh Circuit affirmed that a Georgia land partnership's charitable deduction for a conservation easement was limited to cost basis, plus a 40 percent penalty, a warning for real estate investors in syndicated easement deals.
The uniform deal announced in May is closed and its deadlines withdrawn. Investors in syndicated easement partnerships now face case-by-case talks with a new dedicated IRS office.
Fact Sheet FS-2026-14 restates the 30% cap after the depreciation add-back returned, sets a $32 million small-business test for 2026 and spells out what electing real estate firms give up.
Proposed rules published August 17 would drop a charitable information return for family trusts whose only deduction flows from a partnership or S corporation they own.
The regulations explain how a business can fund children's Trump accounts as an employee benefit, and how nondiscrimination tests limit programs that favor owners and top earners.
Current and former staff sold stock in the company's third tender offer. How much they keep depends on holding periods, how the shares were acquired and, for many, California's treatment of gains.
Guidance on the now-permanent Section 45S credit explains how companies can base the credit on leave insurance premiums and extends eligibility to part-timers working 20 hours a week.
Rep. Jodey Arrington's proposal would stop digital-asset investors from selling at a loss and buying right back, closing a gap that has made crypto the last easy venue for loss harvesting.
In Lewis v. Commissioner, the court rejected both the IRS's $53.4 million figure and the family's $156,000 claim, holding that state law and an avoided tax-reimbursement duty set the value.
Treasury adopted its 2024 proposal without change, so owners who ran a business sale through a charitable remainder annuity trust and a commercial annuity now face mandatory disclosure.
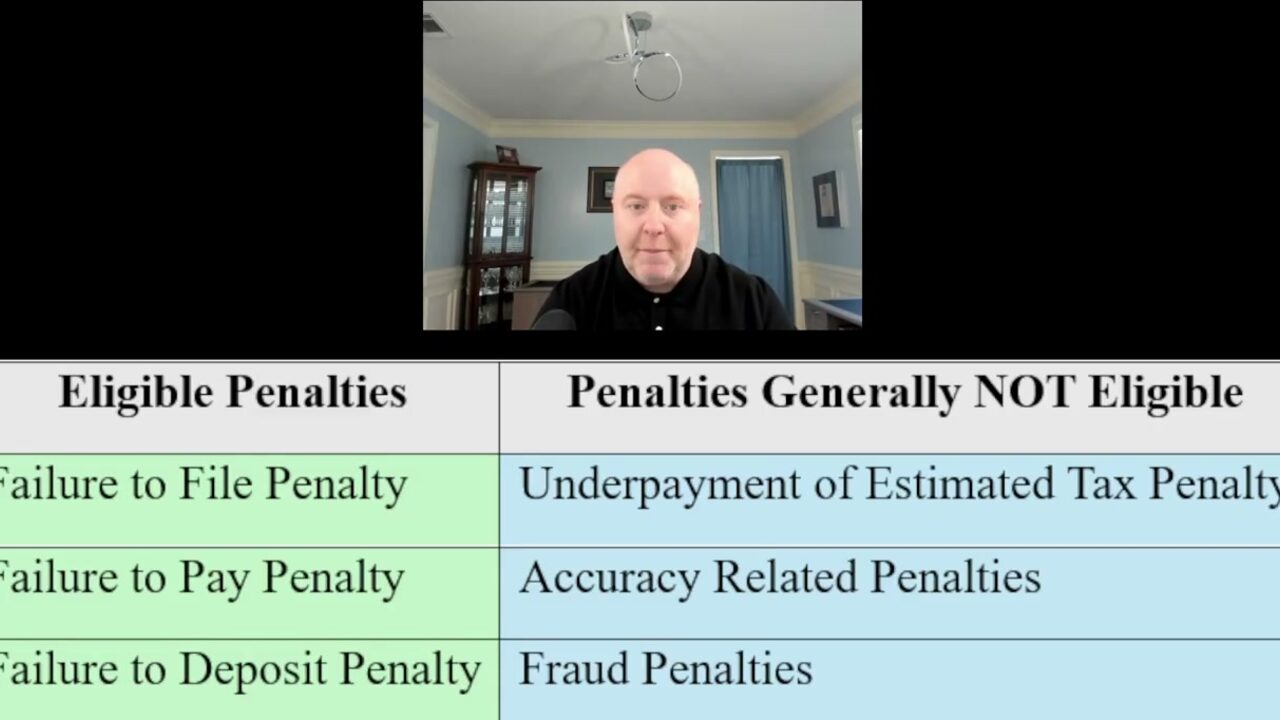
Under Automatic Exemption from Penalty, late-filing, late-payment and deposit penalties are waived during processing for taxpayers with three clean years, with no phone call or request needed.
Contributions opened July 4 and the first investments followed on July 6. Families can put in after-tax money, but growth is taxed as ordinary income once the child reaches adulthood.
Treasury said philanthropists can now transfer publicly traded stock directly into Trump Accounts, opening a new giving channel days before pledges from Michael and Susan Dell and SpaceX's Gwynne Shotwell.
Treasury opened nominations on July 1 with 25,332 eligible tracts, tighter income tests and a 30% basis step-up for rural funds, while original zones and their deferred gains run out on Dec. 31.
Retroactive to January 2026, New Jersey's FY27 budget cuts off the personal offset tied to the state's pass-through entity tax for owners with more than $1 million in income.