Media
Videos
The best explainers on each story we cover, from advisors, institutions and newsrooms.
Rep. Jodey Arrington's proposal would stop digital-asset investors from selling at a loss and buying right back, closing a gap that has made crypto the last easy venue for loss harvesting.
In Lewis v. Commissioner, the court rejected both the IRS's $53.4 million figure and the family's $156,000 claim, holding that state law and an avoided tax-reimbursement duty set the value.
In Beveled Edge Insurance, the court said the codified economic substance doctrine can strip a captive's tax benefits without erasing the whole arrangement, and left penalties on the table for trial.
Automated tax-loss harvesting is nearly standard at 79% of platforms, but fewer than half offer help moving a portfolio and only 21% offer tax-smart withdrawals, Cerulli's survey shows.
Treasury adopted its 2024 proposal without change, so owners who ran a business sale through a charitable remainder annuity trust and a commercial annuity now face mandatory disclosure.
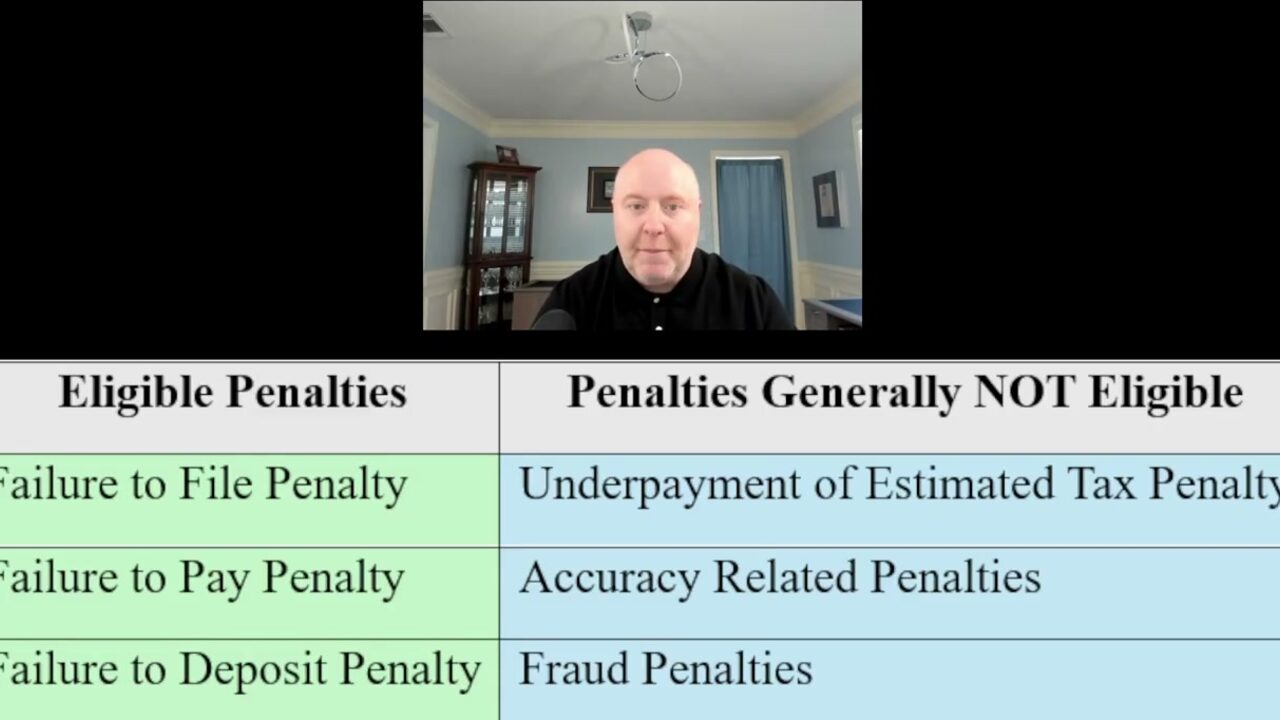
Under Automatic Exemption from Penalty, late-filing, late-payment and deposit penalties are waived during processing for taxpayers with three clean years, with no phone call or request needed.
Contributions opened July 4 and the first investments followed on July 6. Families can put in after-tax money, but growth is taxed as ordinary income once the child reaches adulthood.
Treasury said philanthropists can now transfer publicly traded stock directly into Trump Accounts, opening a new giving channel days before pledges from Michael and Susan Dell and SpaceX's Gwynne Shotwell.
Treasury opened nominations on July 1 with 25,332 eligible tracts, tighter income tests and a 30% basis step-up for rural funds, while original zones and their deferred gains run out on Dec. 31.
Retroactive to January 2026, New Jersey's FY27 budget cuts off the personal offset tied to the state's pass-through entity tax for owners with more than $1 million in income.
UBS's Global Wealth Report 2026 found the US added more new dollar millionaires than any other country, a milestone that turns first-time wealth into first-time exposure to estate and capital gains tax.
Rev. Proc. 2026-25 treats contributions as present-interest gifts eligible for the $19,000 annual exclusion, but one extra gift or a Form 709 filed for another reason can undo the relief.
With the $15 million per-person estate exemption confirmed in effect for 2026, wealthy families are funding dynasty trusts and SLATs this year rather than waiting, even without the old deadline pressure.
Giving USA's annual report found total giving topped $600 billion for the first time in 2025, with bequests growing faster than any other funding source ahead of new 2026 deduction limits.
By declining to hear Murrin v. Commissioner, the justices let stand a Third Circuit ruling that the IRS can assess tax at any time on a fraudulent return, even when only the preparer intended to cheat.
PLR 202625012 says a private foundation has no interest in family business shares until a trustee irrevocably names it, which lets relatives and the company buy stock without self-dealing.
The measure taxes residents as of January 1, 2026, values their wealth at year-end and lets payers stretch the bill over five years, at a price that reaches deep into illiquid founder stock.
The 25th How America Saves study shows record 401(k) participation and savings rates, but finds most high earners still leave mega-backdoor Roth and after-tax contribution room unused.
Second-quarter estimated payments for 2026 are due June 15. High earners with equity vests, gains or K-1 income face a stricter prior-year test, and IRS underpayment interest runs at 6% to 7%.
Gov. Dan McKee signed a $15.2 billion budget that adds one percentage point a year for three years on income above $1 million, taking the top rate from 5.99% to an effective 8.99%.
SpaceX priced the largest IPO in history at $135 a share, but the flat 22% withholding on employee RSUs falls well short of what many will actually owe.
The 2026 Trustees Report pulls the retirement trust fund's depletion forward a year and widens the 75-year gap by 16%, partly because the 2025 tax law cut revenue from taxing benefits.
The fund industry has asked Treasury for guidance on Section 351 ETF conversions after officials discussed labeling some of the deals a tax-avoidance "transaction of interest."
The IRS said 27 states have elected into the new Section 25F credit for gifts to scholarship granting organizations, a dollar-for-dollar option that compares favorably with a normal charitable deduction.